Bank Indonesia Eases Liquidity to Support Productive Lending
Bank Indonesia is adjusting bank liquidity incentives and securities issuance to support lending to productive sectors as credit growth outpaces deposit growth. The measures include a December 2026 change to reserve relief, but a banking analyst cautions that their impact will depend on businesses' demand for financing.
Reserve relief and lending commitments
Bank lending rose 13.26 percent year-on-year in September 2026, compared with 8.22 percent growth in third-party funds, according to figures released following Bank Indonesia's October 20-21 Board of Governors' meeting. The central bank is responding to that gap by giving banks more flexibility to fund productive lending.
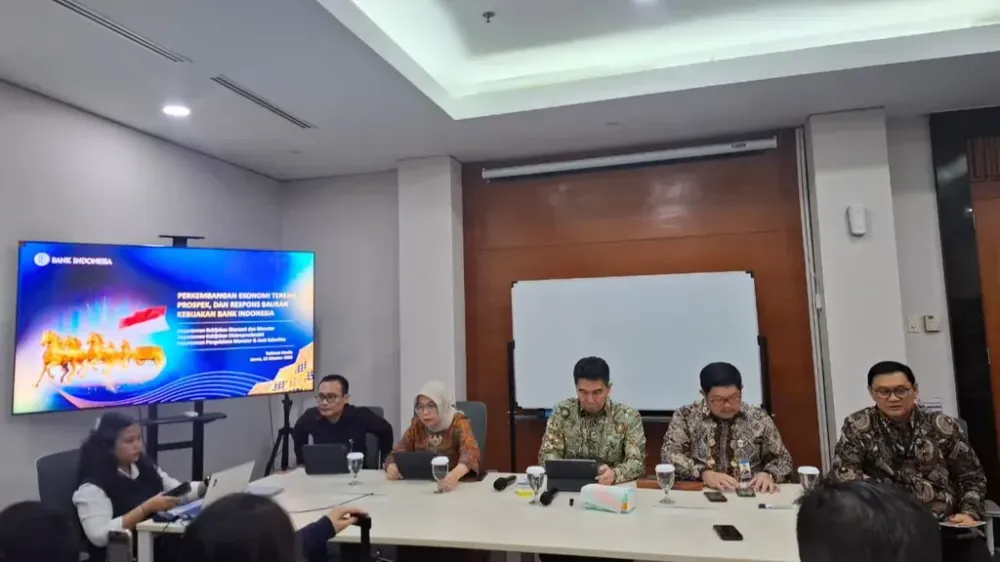
Maulisa Yanti Nasution, head of BI's Macroprudential Policy Department, told reporters in Jakarta on October 23 that the financing-scheme incentive under the Macroprudential Liquidity Incentive Policy (KLM) would fall by 1 percentage point in December. The ceiling for KLM relief will move from 6 percent to 5 percent. BI says this adjustment lowers the minimum reserves banks must hold at the central bank, releasing funds for lending.
The planned change follows an earlier expansion. According to a BI press release, the maximum total KLM incentive rose from 5.5 percent to 6.0 percent of third-party funds effective September 2026. Banks had received Rp446.5 trillion in incentives by early August, equivalent to 5.02 percent of third-party funds.
Maulisa said the financing scheme was close to using its full incentive capacity. BI is therefore reviewing whether incentives allocated to established sectors could be redirected to sectors with greater financing needs. Its selection criteria cover unmet demand for bank credit, contributions to employment, and sector performance and risk, particularly non-performing loans (NPLs).
Banks must submit sector-by-sector lending commitments before receiving incentives. BI will assess actual lending against those commitments at the end of the period and adjust the incentives accordingly. Maulisa stressed that each bank remains responsible for its credit decisions and should not force lending into a sector where its own NPL ratio is high.
Conditions for access
BI is retaining a separate 2 percent KLM incentive under the Macroprudential Liquidity Buffer (PLM/PPU) scheme, which reduces banks' minimum liquidity maintenance requirements. To discourage banks from leaving the released funds in non-credit instruments, BI has tightened access through the Macroprudential Intermediation Ratio (RIM). Banks must keep that ratio above 80 percent or continue progressing toward the optimal threshold of 84 percent.
Earlier banking data provide context for the risk requirements. In its second-quarter Monetary Policy Report, BI cited a gross NPL ratio of 2.17 percent, a net NPL ratio of 0.84 percent and a capital adequacy ratio of 23.74 percent in May 2026 as evidence of banking-sector resilience.
A separate expansion of inclusive financing rules took effect on October 1, 2026. The strengthened Macroprudential Inclusive Financing Ratio (RPIM) framework extends eligible lending to corporate suppliers, distributors and business partners. It also broadens cooperation between banks on lending to micro, small and medium-sized enterprises (MSMEs).
Securities issuance and liquidity backstops
Alongside the incentive changes, BI has reduced auctions of Bank Indonesia Rupiah Securities (SRBI) from weekly to once every two weeks. Erwin Hutapea, head of BI's Monetary Management and Securities Asset Department, said issuance volumes are also being adjusted to limit the amount of bank liquidity absorbed.
The balance absorbed through SRBI has fallen below Rp950 trillion from a peak of Rp1,070 trillion. BI says it has returned approximately Rp150 trillion to the money market. Erwin said the changes aim to balance funds locked up for longer periods with short- and medium-term needs. More adequate daily liquidity is expected to help keep money market rates within BI's target corridor and support the transmission of monetary policy to control inflation.
BI will nevertheless maintain SRBI's appeal as a rupiah-denominated asset, Erwin said. Foreign investors' holdings had risen from Rp238.09 trillion on June 15 to Rp288.65 trillion on July 20, 2026, when they accounted for 27.11 percent of total SRBI outstanding, according to BI's second-quarter report.
The securities strategy accompanies stronger foreign-exchange hedging incentives. In measures announced in July, BI increased the Hedge Sell Swap incentive from 10 percent to 12.5 percent and introduced a 15 percent incentive for Hedge Sell Domestic Non-Deliverable Forward (DNDF) transactions. BI said those measures were intended to attract foreign portfolio investment and support rupiah stability.
Banks facing a temporary cash shortfall also have access to BI's emergency liquidity facilities if they cannot find money market counterparties. Access has no fixed limit, provided banks hold sufficient underlying assets. The facilities address the mismatch that can arise when short-term deposits fund long-term loans.
Banks holding Government Securities (SBN) or SRBI can obtain liquidity through repos with terms ranging from one week to 12 months. Those without either security but with foreign-currency liquidity can use regular swap transactions.
Demand remains the constraint
Credit had already been accelerating before September. BI's second-quarter report recorded year-on-year loan growth of 12.67 percent in June 2026, up from 11.51 percent in May. June growth was 24.90 percent for investment loans, 8.94 percent for working capital loans and 5.75 percent for consumer loans.
In that report, BI projected full-year 2026 credit growth of 8-12 percent. It cited potential demand reflected in Rp2,490 trillion of undisbursed loan facilities as of June, equivalent to 21.52 percent of available credit lines.
Trioksa Siahaan, a banking analyst and senior vice president at the Indonesian Banking Development Institute (LPPI), said reserve easing and KLM incentives could expand banks' financing capacity without necessarily producing a substantial increase in productive lending. He considers aggregate banking liquidity relatively adequate; the more fundamental constraints are businesses' ability to absorb financing, the demand outlook, prospective borrowers' quality and banks' management of credit risk.
"Additional liquidity is likely to be allocated more towards securities if credit demand remains insufficient," he said on October 23. He said the incentives need support from a better business climate, greater certainty about demand and improved financial viability among MSMEs and productive sectors.
Trioksa said the policy's results should be assessed through actual additional productive lending, economic activity, job creation and credit quality, rather than the amount of liquidity released alone. "Liquidity easing is a supportive factor, but success is heavily dependent on the recovery of healthy credit demand and the banking sector's ability to manage risks," he said.